Effective: 1 October 2026; revised Article 55 rules from the first Tax Year commencing after 1 October 2027
Cabinet Decision No. 149 of 2026 amends the UAE VAT Executive Regulation on profit margin, zero-rating, employee expenses, input tax recovery, apportionment, capital assets, credit notes and composite supplies. The general effective date is 1 October 2026. The revised Article 55 apportionment provisions apply from the first Tax Year commencing after 1 October 2027.
Source documents & MJS briefing
FTA-hosted VAT Executive Regulation, including the September 2026 amendments (English PDF; unofficial translation)The supplied MJS review is a summary, not the government decision. Its reference to awaiting FTA employee-benefit conditions predates Decision No. 17 of 2026; those conditions are now covered in our companion update. Refer to the full legislation for application.
View MJS briefing graphics (3)
Part A — Profit margin, healthcare goods and the outside-the-State test
The MJS comparison identifies the following changes to existing provisions:
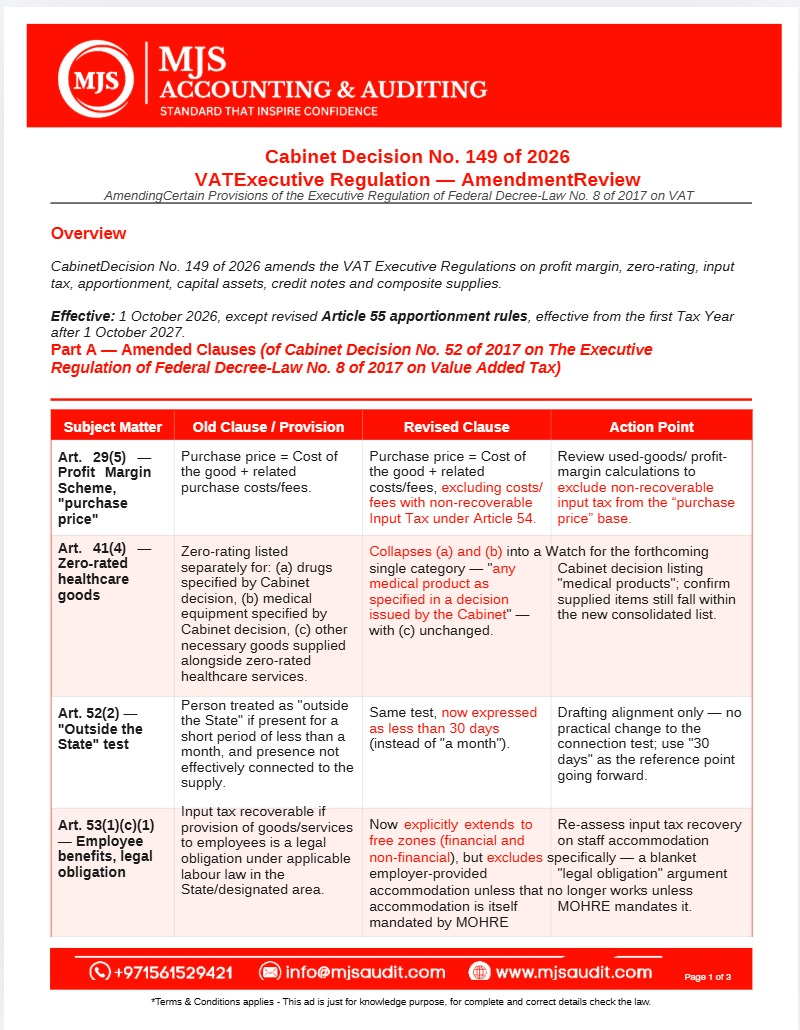
- Article 29(5): The profit-margin purchase-price calculation excludes costs or fees with non-recoverable input tax under Article 54. Review used-goods and profit-margin calculations.
- Article 41(4): The separate drugs and medical-equipment categories are consolidated into medical products specified by Cabinet decision. Check the applicable Cabinet list when classifying supplies.
- Article 52(2): The short-presence test is expressed as less than 30 days, replacing less than a month; presence must still be unconnected with the supply.
Part A — Employee benefits and accommodation
Article 53 distinguishes the legal-obligation route from the contractual-obligation or documented-policy route.
- Article 53(1)(c)(1): The labour-legislation provision expressly includes financial and non-financial free zones. Employer accommodation is excluded from this route unless it is mandatory under Ministry of Human Resources and Emiratisation decisions or directives.
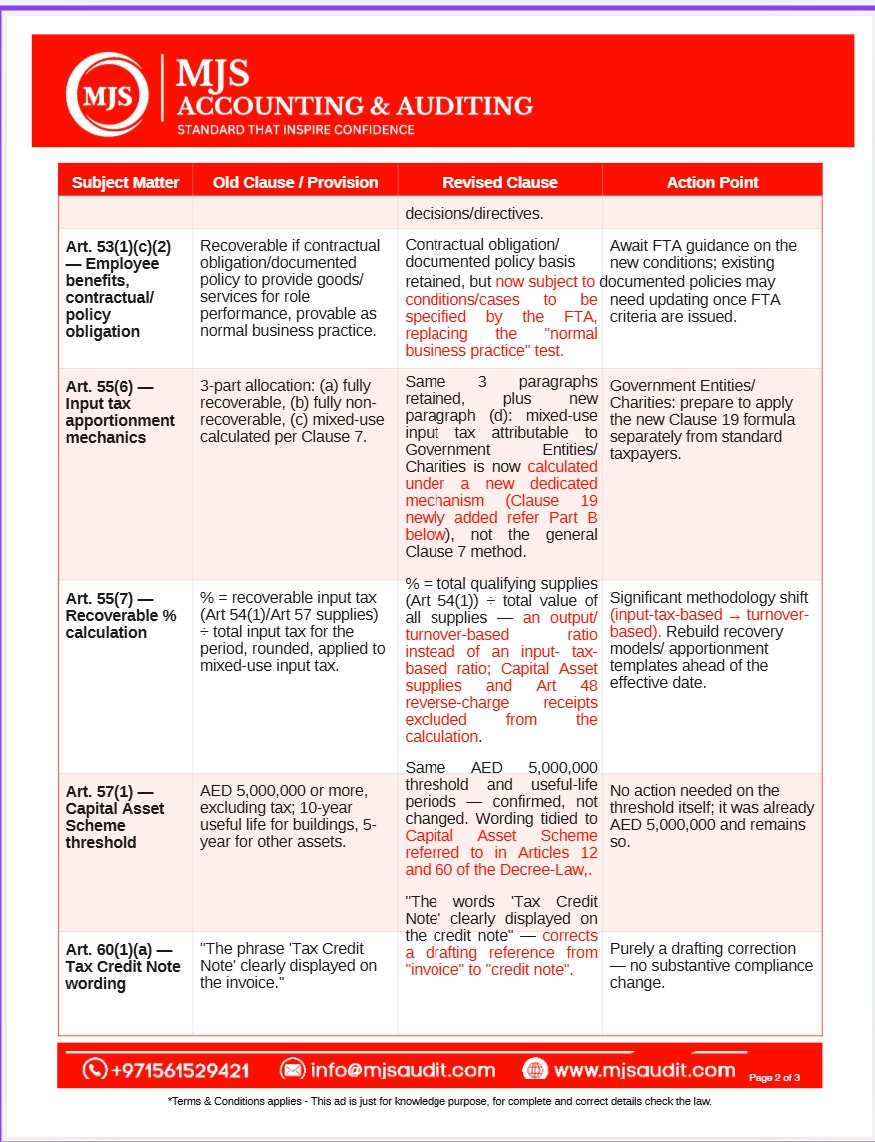
- Article 53(1)(c)(2): A contractual obligation or documented policy must meet the cases and conditions specified by the FTA. Decision No. 17 of 2026 now sets out those conditions for six employee-expense categories.
Part A — Input tax apportionment: a later commencement date
The amended Article 55(6), Article 55(7) and new Article 55(19) apply from the first Tax Year commencing after 1 October 2027. Businesses should establish the commencement date for their own Tax Year before changing their calculation.
- Article 55(6): Full recovery, non-recovery and mixed-use allocation remain distinct. A separate mixed-use rule is introduced for Government Entities and Charities.
- Article 55(7): For other taxable persons, the standard recovery percentage changes from an input-tax-based calculation to qualifying supplies under Article 54(1) divided by the total value of supplies. Capital Asset supplies and Article 48 reverse-charge receipts are excluded.
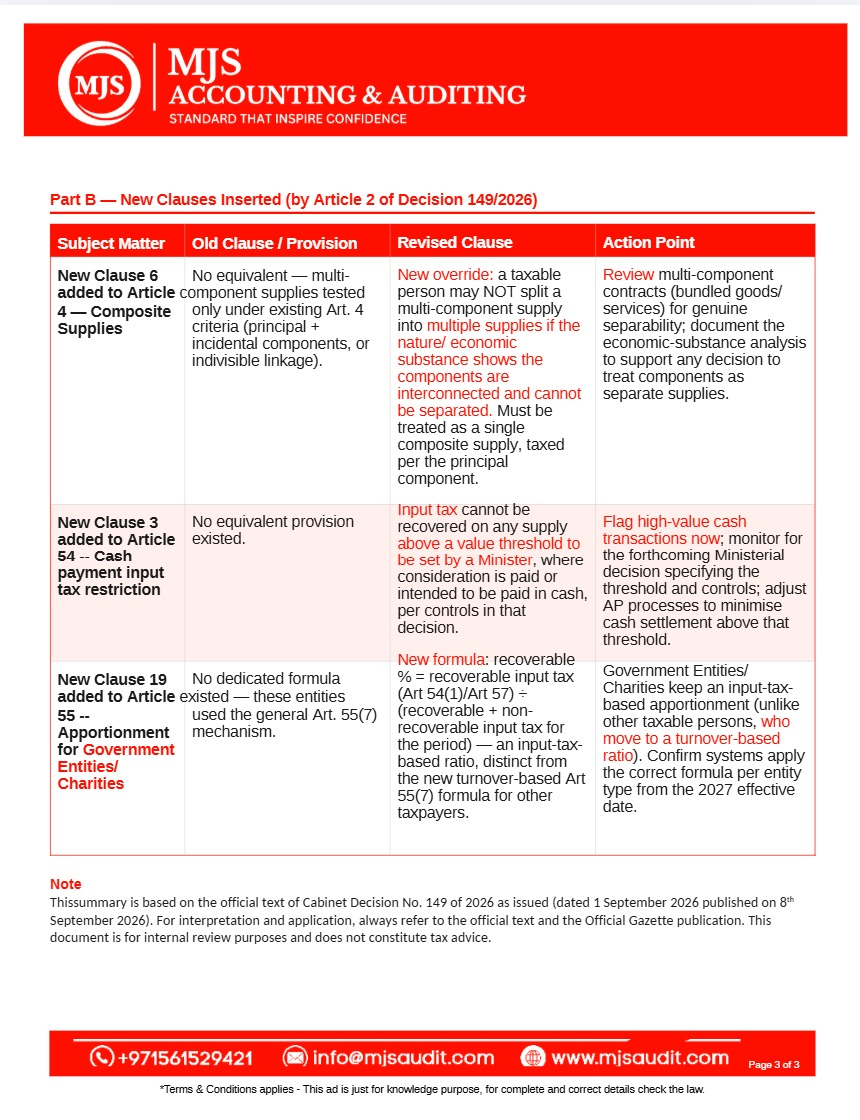
- Article 55(19): Government Entities and Charities use a dedicated input-tax ratio: recoverable input tax under Article 54(1)/Article 57 divided by total recoverable and non-recoverable input tax for the period.
Part A — Capital assets and tax credit notes
- Article 57(1): The AED 5,000,000 threshold excluding VAT remains unchanged, together with useful-life thresholds of 10 years for buildings and 5 years for other assets. The wording is aligned with the Capital Asset Scheme references.
- Article 60(1)(a): The words ‘Tax Credit Note’ must appear on the credit note. The amendment corrects the earlier reference to an invoice.
Part B — New composite-supply and cash-payment provisions
- New Article 4(6): Interconnected components that cannot be separated in economic substance cannot be treated as multiple supplies. They are treated as one composite supply according to the principal component. Review bundled contracts and document the analysis.
- New Article 54(3): Input tax recovery is restricted for supplies above a value specified by Ministerial decision where payment is made or intended in cash, subject to that decision’s controls. The amendment itself does not specify a numeric threshold; check the applicable Ministerial decision before applying a limit.
- New Article 55(19): The dedicated Government Entity and Charity apportionment mechanism follows the later Article 55 commencement date described above.
Official Regulatory References & Citations:
Have questions regarding this regulation?
Connect directly with MJS Accounting & Auditing experts via WhatsApp or schedule an office consultation.